Build Wealth with San Diego Real Estate
Real Estate, San Diego Homeownership, Wealth Building
Building Wealth Through San Diego Real Estate: A Homeowner's Guide
For homeowners in San Diego and Chula Vista, your property is more than a place to live—it is a powerful financial asset. With thoughtful strategy, you can turn today's home into tomorrow's long-term wealth, even in a market that feels expensive and complex.
1. Understand Your Home Equity Growth
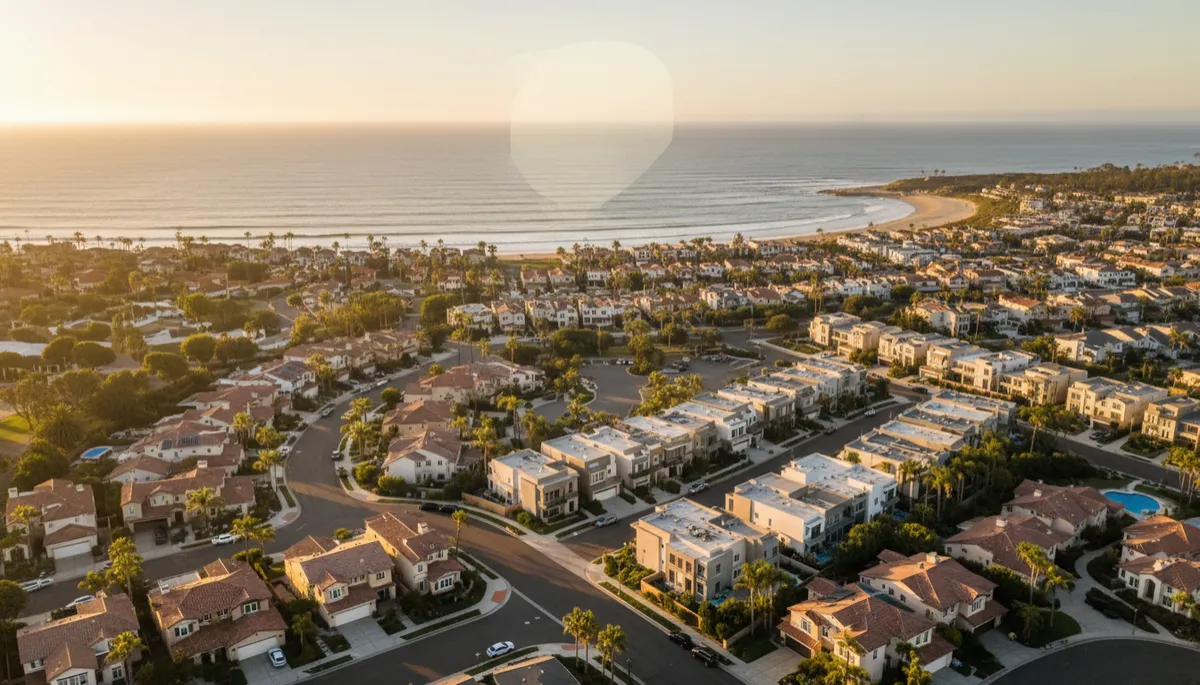
Home equity is the foundation of real estate wealth. It is the difference between what your home is worth and what you still owe on your mortgage. In San Diego County, single-family homes have continued to appreciate modestly, with detached homes up roughly 2–4.5% year-over-year in early 2026, and the median single-family price reaching around $1.1 million by March 2026 (Juniper Real Estate; CoreLogic via mothebroker.com). Despite some softening in condos and townhomes, an estimated 58% of local properties are considered "equity-rich," meaning owners have substantial equity to work with.
For homeowners in neighborhoods like East Chula Vista, where recent data shows median prices around $1.125 million with year-over-year gains of about 6.3%, equity can accumulate quickly. Even West Chula Vista, with a median near $828,600 and a modest 3.1% decline, still offers significant long-term equity potential when combined with principal paydown over time.
2. Refinancing Strategies to Unlock and Protect Wealth
With mortgage rates hovering in the mid-6% range in 2026, refinancing requires careful analysis. However, for many San Diego and Chula Vista homeowners, strategic refinancing can still be a valuable tool to either lower monthly payments or access equity for other investments.
- Rate-and-term refinance: If rates dip closer to the mid-5% range, as some forecasts suggest, refinancing to a lower rate can improve cash flow and accelerate principal reduction without increasing your loan balance.
- Cash-out refinance or HELOC: Equity can be tapped to fund renovations, pay off higher-interest debt, or seed a down payment on a rental property. This can be effective when used for productive investments, not lifestyle spending.
Before refinancing, run detailed scenarios with a lender or financial advisor: compare total interest paid over the life of the loan, closing costs, and your time horizon in the home. In an appreciating market like much of coastal San Diego, preserving flexibility—such as avoiding excessive cash-out that leaves you overleveraged—is essential.
3. Turning Your Home Into Rental Income
Rental income can transform your primary residence or a second home into a long-term wealth engine. While San Diego's rental market is currently under pressure—with median asking rents down roughly 3–7% year-over-year in early 2026 and vacancy around 5.4%—well-located properties still offer strong income potential, especially near the coast or major employment hubs (managecasa.com; realtor.com; libuttira.com).
- Traditional long-term rentals: Converting a former primary residence in Chula Vista or San Diego into a rental when you move up to a new home can create steady cash flow and ongoing equity growth. Focus on tenant retention, property condition, and realistic pricing to reduce vacancy in today's competitive market.
- Accessory dwelling units (ADUs): Adding a permitted ADU or converting a garage can create an additional income stream. In high-demand neighborhoods, an ADU can command meaningful rent while also boosting overall property value.
Short-term rentals can offer higher gross revenue—recent averages show about $4,273 per month with an average daily rate near $350—but they require professional management, strong compliance with local regulations, and tolerance for income volatility. For most homeowners focused on steady wealth building, a well-managed long-term rental or ADU is often the more predictable path.
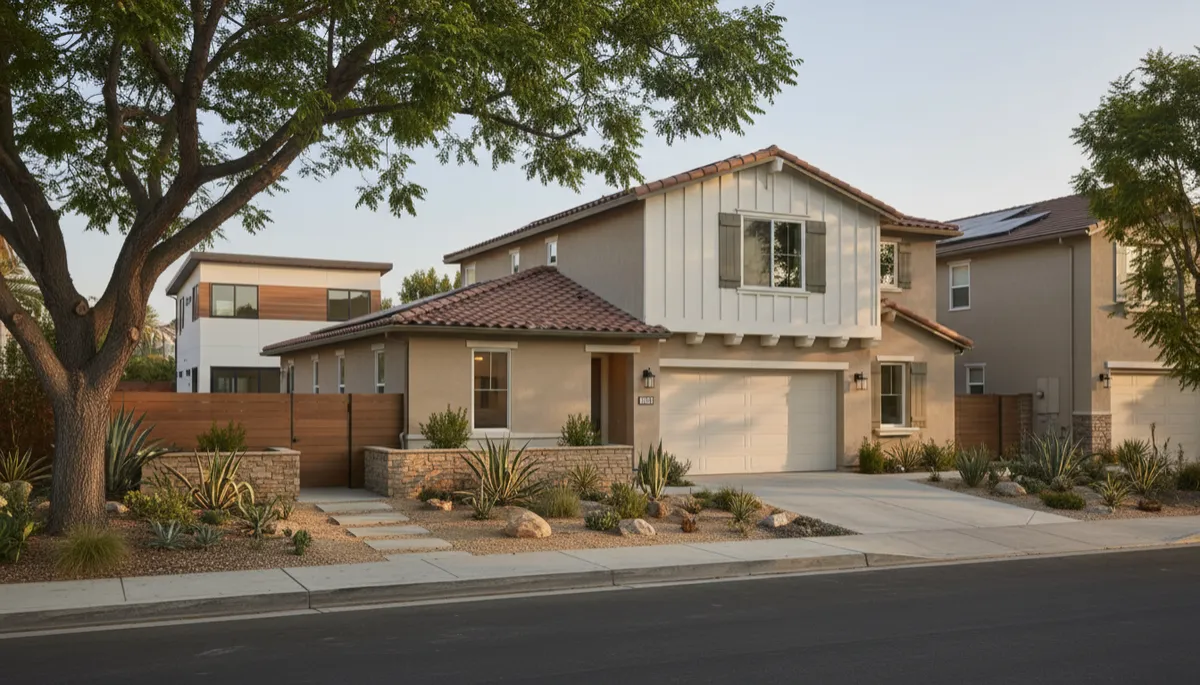
Adding an ADU can create reliable rental income while increasing overall property value.
4. Leveraging 1031 Exchanges to Scale Your Portfolio
For owners of rental property in San Diego or Chula Vista, a 1031 exchange is a powerful tool for building wealth. This IRS provision allows you to defer capital gains taxes when you sell an investment property and reinvest the proceeds into another "like-kind" investment property, following strict timelines and rules.
In practice, this might mean selling a condo in a softening downtown market and exchanging into a single-family rental in East Chula Vista or a duplex closer to employment centers. By deferring taxes, you keep more capital working for you, potentially upgrading into properties with stronger cash flow, better appreciation prospects, or both. Because 1031 exchanges are technical, work closely with a qualified intermediary, tax professional, and local real estate advisor before listing your property.
5. Local Market Appreciation: Why Location Still Matters
The San Diego region is not a single market; it is a collection of micro-markets. Recent data shows North Park up nearly 14% year-over-year, East Chula Vista up over 6%, and Bonita down around 16%. Inventory remains tight, with many areas still under three months of supply—well below a balanced market. Forecasts for 2026 call for flat to modest appreciation of 0–5% countywide, with select neighborhoods outperforming.
For homeowners, this means that strategic decisions about upgrades, timing a move, or purchasing a second property should consider neighborhood-level trends. Areas with strong employment access, good schools, and limited new supply—such as parts of East Chula Vista, coastal communities, and central neighborhoods—are more likely to sustain long-term appreciation, supporting your overall wealth plan.
6. Smart Financial Moves for San Diego and Chula Vista Homeowners
- Maintain a long-term mindset: Short-term price swings are normal. Focus on a 7–10+ year horizon, during which moderate annual appreciation and principal paydown can significantly increase your net worth.
- Prioritize high-ROI improvements: In a competitive market, upgrades such as modern kitchens, energy-efficient windows, and improved curb appeal can enhance both resale value and rental income potential.
- Protect your downside: Maintain adequate cash reserves for repairs, vacancies, and unexpected expenses. Consider fixed-rate financing to shield yourself from interest-rate volatility.
- Align real estate with your overall plan: Coordinate decisions about refinancing, adding rentals, or executing a 1031 exchange with your tax advisor and financial planner so that property strategy supports retirement, education, and legacy goals.
Final Thoughts: Turning Your Home Into a Strategic Asset
Building wealth through San Diego real estate does not require perfect timing or speculative risk. It requires clarity about your goals, an understanding of local trends in neighborhoods like Chula Vista, North Park, and beyond, and a willingness to use the tools available to homeowners: equity growth, smart refinancing, rental income, and tax-efficient strategies such as 1031 exchanges. With guidance from experienced local professionals and a long-term perspective, your home can become one of the most reliable wealth-building assets in your financial life.
SEO Title: Building Wealth Through San Diego Real Estate: A Homeowner's Guide
Meta Description: Discover how San Diego and Chula Vista homeowners can build long-term wealth through home equity growth, refinancing, rental income, 1031 exchanges, and smart financial strategies tailored to the local market.
BOOK AN APPOINTMENT WITH US TODAY!
What Our Clients are Saying
Martin Barros